India’s aviation sector, currently one of the fastest-growing in the world, is standing at a critical regulatory crossroads. As the country seeks to expand its domestic fleet and establish new carriers to meet soaring passenger demand, a fundamental question has emerged: Should the entities that control the nation’s airports also be permitted to own and operate the airlines that fly out of them?
The debate, which goes to the heart of market competition and antitrust policy, was officially reopened by Civil Aviation Minister K. Rammohan Naidu. Speaking to reporters, Naidu confirmed that the government is actively evaluating the "pros and cons" of relaxing long-standing restrictions that prevent airport operators from holding major stakes in commercial airlines.
"Airports and airlines together operating needs some deliberation," Naidu stated, acknowledging the complexity of the issue. "We are going to see the pros and the cons of it."
While the government has yet to make a final decision, the minister’s comments have reignited a policy debate that India’s regulatory framework had seemingly settled nearly two decades ago.
The Catalyst: Adani’s Quest for a Regulatory Waiver
The immediate trigger for this policy review is a formal request from Adani Airport Holdings, the country’s largest private airport operator. The company has approached the Airports Authority of India (AAI) seeking a waiver from a key restrictive clause in its concession agreements.
Specifically, Adani is seeking relief from regulations that prevent the operator of Mumbai’s Chhatrapati Shivaji Maharaj International Airport (CSMIA) from holding more than a 10% equity stake in a scheduled passenger airline.
Under current rules, this cross-holding cap is designed to prevent vertical integration in the aviation supply chain. By keeping airport operations strictly separated from airline ownership, the policy aims to ensure a level playing field for all air carriers.
However, Adani’s petition has forced the Ministry of Civil Aviation and the AAI to reconsider whether these rules, drafted during the initial wave of airport privatization in the mid-2000s, remain appropriate for India’s modern aviation landscape.
The Historical Context: Why the 10% Cap Was Created
To understand the gravity of the current debate, it is necessary to look back to the mid-2000s, when the Indian government decided to privatize its primary gateway airports in Delhi and Mumbai.
Through the landmark Operation, Management and Development Agreement (OMDA), the government handed over the operations of these vital hubs to private consortia—GMR Group for Delhi and GVK Group for Mumbai (the latter’s share was subsequently acquired by the Adani Group).
During the drafting of the OMDA, regulators and antitrust experts raised significant concerns about the potential for market distortion. If a private company controlled a highly congested, slot-constrained airport like Mumbai or Delhi, and also owned a commercial airline, it would face an inherent conflict of interest.
To prevent anti-competitive behavior, the government instituted the 10% cross-holding limit. The rationale was clear:
- Fair Slot Allocation: Airport operators control the allocation of takeoff and landing slots. An operator with an ownership stake in an airline would be incentivized to award the most lucrative slots to its own carrier.
- Nondiscriminatory Pricing: Airports charge airlines various aeronautical fees, including landing, parking, and passenger service charges. A neutral operator ensures these fees are applied uniformly.
-
Access to Infrastructure: From
ticket counters and baggage carousels to boarding gates and hangar space, physical airport infrastructure is finite. Independent oversight ensures that dominant carriers cannot monopolize these resources to the detriment of newer or smaller competitors.
For nearly twenty years, this regulatory wall has stood firm, keeping the businesses of infrastructure management and air transport separate.
Weighing the Pros: The Arguments for Relaxation
Proponents of changing the current rules argue that India’s aviation sector has matured to a point where vertical integration could yield substantial economic benefits.
Infusion of Patient Capital
Airlines are notoriously capital-intensive, low-margin businesses susceptible to external shocks, from fuel price volatility to geopolitical tensions. India has seen numerous airlines go bankrupt over the last two decades, including Kingfisher Airlines, Jet Airways, and more recently, Go First.
Large infrastructure conglomerates, such as the Adani Group, possess the deep pockets and long-term investment horizons needed to sustain and scale commercial carriers. Allowing these giants to invest heavily in airlines could bring much-needed financial stability to the sector.
Operational Synergies and Efficiency
In theory, an integrated aviation company could create a more seamless travel experience. By coordinating airport terminal design, baggage handling systems, and digital check-in ecosystems directly with airline operations, an integrated operator could reduce transit times, optimize aircraft turnaround times, and lower overall operational costs. These efficiencies could, in turn, be passed down to consumers in the form of lower ticket prices.
Accelerating Regional Connectivity
The Indian government has been highly focused on its UDAN (Ude Desh ka Aam Naagrik) regional connectivity scheme, which aims to make flying affordable and widespread. Airport operators with stakes in regional airlines might be more willing to operate unprofitable or low-margin routes connecting tier-2 and tier-3 cities, cross-subsidizing those operations with revenues generated from major metropolitan airports.
Weighing the Cons: The Risk of Market Distortion
Conversely, critics and independent aviation analysts warn that dismantling the barrier between airports and airlines could lead to severe market imbalances.
+-----------------------------------------------------------------+
|               POTENTIAL RISKS OF VERTICAL INTEGRATION           |
+-----------------------------------------------------------------+
|  1. Preferential Slot Allocation                                |
|     - Best departure/arrival times given to affiliate airline.  |
|                                                                 |
|  2. Discriminatory Pricing & Fees                               |
|     - Hidden discounts or rebates for the home carrier.         |
|                                                                 |
|  3. Monopolization of Airport Infrastructure                    |
|     - Prime gates, check-in counters, and hangars restricted.   |
|                                                                 |
|  4. Barriers to Entry for New Competitors                       |
|     - Startups unable to secure viable slots or space.          |
+-----------------------------------------------------------------+
The Battle for Slots at Congested Hubs
The primary concern is the allocation of landing and takeoff slots, particularly at capacity-constrained airports like Mumbai’s CSMIA. Mumbai Airport operates with a single intersecting runway system, making slots incredibly scarce and highly valuable.
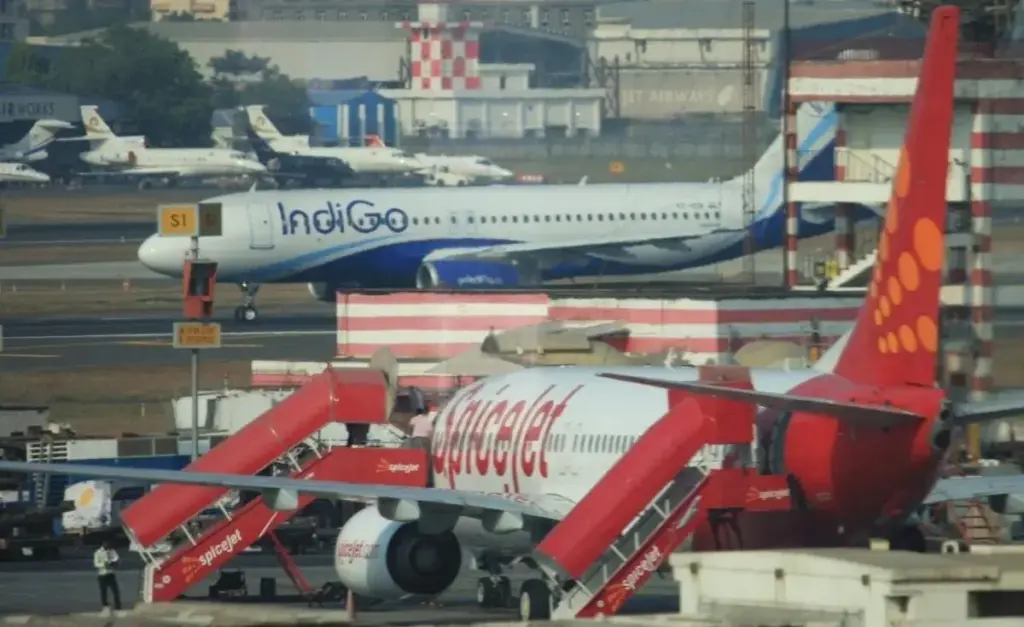
If the operator of CSMIA is permitted to own a major stake in an airline, competing carriers like IndiGo, Air India, SpiceJet, and Akasa Air would understandably worry about preferential treatment. Even the perception of bias in slot allocation could lead to protracted legal battles and regulatory uncertainty.
Anti-Competitive Ecosystems
An airport operator controls a vast array of ground services, including cargo handling, fuel farm access, catering services, and maintenance hangars. If an operator-owned airline receives priority access or discounted rates for these essential services, independent airlines would find themselves at a severe cost disadvantage, stifling healthy market competition.
Regulatory Overreach and Conflict of Interest
The Airports Authority of India (AAI) and the Directorate General of Civil Aviation (DGCA) would face an incredibly complex task in monitoring transactions between an airport operator and its sister airline. Ensuring "arm’s length" transactions in such an environment requires highly sophisticated regulatory oversight, which could strain existing administrative resources.
The Global Precedent: How Other Markets Handle the Issue
As India deliberates on this policy shift, it will likely look to international precedents. Globally, the separation of airport management and airline operations is a widely accepted regulatory standard, though there are notable exceptions.
- The European Union: EU regulations strictly enforce the principle of effective unbundling. Airport operators are generally prohibited from controlling airlines to ensure fair competition across the single European sky.
- The United States: In the U.S., airports are almost exclusively owned by local or state public authorities rather than private corporations, naturally preventing private vertical integration with commercial airlines.
- The Middle East: In hubs like Dubai and Doha, the state owns both the primary airport and the flag carrier (e.g., Emirates and Dubai Airports, or Qatar Airways and Hamad International Airport). While this model has driven rapid, highly coordinated growth, it operates under a unique state-directed economic model that differs significantly from India’s privatized, competitive market dynamics.
What Lies Ahead for India’s Aviation Policy?
The decision facing Civil Aviation Minister K. Rammohan Naidu and the Indian government is not an easy one. On one hand, India needs more aircraft, more airlines, and robust capital investment to support its target of becoming a global aviation hub. On the other hand, safeguarding the competitive integrity of the market is paramount to protecting consumer interests and encouraging fair play among existing private carriers.
Should the government decide to grant the waiver requested by Adani Airport Holdings, it will likely have to introduce a stringent ring-fencing framework. Such a framework would need to guarantee absolute transparency in slot allocation, third-party audits of aeronautical charges, and strict non-discriminatory access to all airport infrastructure.
As the Ministry of Civil Aviation continues its deliberations, the entire industry—from established legacy carriers to ambitious infrastructure conglomerates—will be watching closely. The outcome of this review has the potential to fundamentally reshape the economics of flying in India for decades to come.