In the global hospitality industry, corporate success is traditionally broadcast through a highly standardized set of vanity metrics. Quarterly earnings calls and press releases routinely champion the expansion of the development pipeline: the number of new properties signed, the volume of rooms added to the system, and the rapid growth of brand portfolios. These metrics are clean, easily quantifiable, and highly favored by public equity markets.
However, these numbers often obscure a fundamental tension at the heart of modern hotel management. While rapid room growth benefits the corporate brand operator, it says very little about the actual economic reality of the individual property owner. For the real estate investors, institutional funds, and family offices that write the checks, a hotel is not merely a flag on a map—it is a capital-intensive asset that must generate a competitive return on investment.
"Net unit growth is an entirely logical measure for an asset-light operator," says Wayne Williams, Chief Financial Officer of Minor Hotels. "It shows how efficiently the system is expanding and how future revenues and fee streams are generated. However, you shouldn’t confuse that with an owner metric."
As macroeconomic pressures reshape the hospitality landscape, the divergence between operator metrics and owner realities is becoming harder to ignore. With elevated capital costs, rising construction expenses, and persistent labor and supply chain delays, the margin for error in hotel development has shrunk dramatically. Today, the quality of hotel growth is becoming far more critical than its sheer pace.
The Scorecard Disconnect: Net Unit Growth vs. Owner EBITDA
To understand the tension between owners and operators, one must look at their respective scorecards. An operator operating under a pure play, asset-light fee model is incentivized to maximize system-wide top-line revenue, which directly feeds their management and franchise fees. For these operators, Net Unit Growth (NUG) is the primary engine of valuation.
For the property owner, however, top-line revenue is only the beginning of the equation. The owner’s scorecard is focused on bottom-line performance:
- EBITDA Conversion: How effectively does a dollar of revenue translate into earnings before interest, taxes, depreciation, and amortization?
- Cash Generation: What is the actual free cash flow available to service debt and distribute to equity partners after accounting for capital reserves?
- Cost Flexibility: Can the property’s operating model flex downward during demand downturns to protect margins, or is it burdened by rigid brand standards and fixed overhead?
- Return on Invested Capital (ROIC): Is the capital committed to the asset earning a yield that justifies the risk, particularly when risk-free rates are substantially higher than they were five years ago?
In the current development environment, the financial stakes of aligning these two scorecards are exceptionally high. A capital allocation decision made at the signing of a hotel management agreement carries long-term consequences. If an operator pushes for a costly brand-mandated design standard or an expensive food and beverage concept that fails to resonate with the local market, the operator’s financial downside is minimal, but the owner’s capital is directly impaired.
The Reality of the "Asset-Light" Shift
Over the past two decades, the world’s largest hospitality companies have aggressively transitioned to asset-light business models, divesting their real estate holdings to focus exclusively on franchising and brand management. This strategy has allowed operators to scale at unprecedented speeds, enter new international markets with minimal capital expenditure, and build massive distribution systems and loyalty programs.
Yet, this shift has created an inherent alignment challenge. While the operator’s balance sheet has been lightened, the physical reality of the hotel industry remains capital-heavy.
"The underlying hotel hasn’t suddenly become light," Williams points out. "What changes in an asset-light model is the responsibility. It’s someone else’s money at risk, and operators need to act accordingly."
This shift in responsibility introduces a critical alignment test for any proposed capital expenditure. When a brand operator recommends a comprehensive property renovation, a major technology infrastructure upgrade, or a costly brand repositioning, a fundamental question must be asked: Would the operator make the same recommendation if they were spending their own capital?
Without a shared exposure to the financial consequences of these decisions, the relationship between owner and operator can easily become transactional, with the operator prioritizing brand standardization over property-level profitability.
The Hybrid Model: Maintaining Capital Exposure in an Asset-Light Pipeline
Minor Hotels, a global hospitality group with a portfolio of over 550 hotels, occupies a unique position in this debate. Unlike many of its purely asset-light peers, Minor Hotels has retained a substantial real estate footprint. Approximately 70 percent of its existing portfolio is owned, leased, or managed under structures where the company retains direct capital exposure.
At the same time, the company is actively expanding its footprint through asset-light management agreements. More than 85 percent of Minor Hotels’ extended development pipeline is now asset-light, up from roughly 70 percent just a year earlier.
Minor Hotels Portfolio Structure vs. Pipeline Transition

Existing Portfolio:
[██████████████████████████████ 70% ] Owned, Leased, or Capital Exposure
[████████████ 30% ] Pure Asset-Light

Extended Pipeline:
[██████████████████████████████████ 85% ] Asset-Light Deals
[██████ 15% ] Capital Exposure / Equity Deals
This hybrid approach allows the company to capture the rapid scaling benefits of the asset-light model without losing the operational discipline that comes with being a real estate owner. Because Minor Hotels directly feels the weight of financing costs, rising utility bills, labor inflation, and cyclical reinvestment demands across its owned estate, its corporate team views third-party capital with a different level of respect.
According to Williams, this dual identity directly shapes how the company approaches capital allocation and project underwriting. Every development opportunity is scrutinized through an owner’s lens: analyzing the incremental earnings potential, stress-testing the underlying assumptions, assessing downside risks, and evaluating whether the capital might yield a stronger return if deployed elsewhere.
"Capital allocation approval is not the end of the story for us. We keep challenging the assumptions as each project develops," Williams explains. "If the economics change, we may change the scope, phase the investment, delay it, or decide not to proceed."
Case Study: Driving EBITDA Through Strategic Reinvestment in Europe
The practical value of this owner-centric mindset was demonstrated in Minor Hotels’ European portfolio during 2023 and 2024. Rather than focusing solely on expanding its room count through new construction, the company identified 43 existing hotels where targeted capital deployment could unlock significant latent value.
Minor Hotels committed more than $110 million of its own capital to renovate and reposition these 43 properties. Crucially, this capital injection did not add a single new room to the company’s global system—a move that would be counterintuitive for an operator focused strictly on net unit growth metrics.
Instead, the investment was designed to fundamentally alter the operating economics of the existing assets. The results of this disciplined capital deployment were stark:
EBITDA Growth Comparison (2023 - 2025)

Minor Hotels (43 Renovated European Properties):
[████████████████████████████████████████ 40% EBITDA Increase ]

Comparable Competitor Hotels:
[██████████████ 14% EBITDA Increase ]
By 2025, EBITDA across the 43 renovated properties had surged by nearly 40 percent. In comparison, comparable hotels in the same markets experienced an average EBITDA growth of approximately 14 percent over the same period.
"Being accretive to earnings is important, and the path you take to get there matters," says Williams. "It’s counterintuitive to net unit growth, but when you’re focused on earnings, that becomes an important part of how you think about growth."
The Owned Portfolio as an Operational Testing Ground
Beyond financial returns, maintaining an owned portfolio provides an operator with a real-world research and development laboratory. Rather than treating third-party owners’ assets as test subjects for unproven concepts, Minor Hotels utilizes its own balance sheet to trial new guest experiences, brand offerings, and operational technologies.
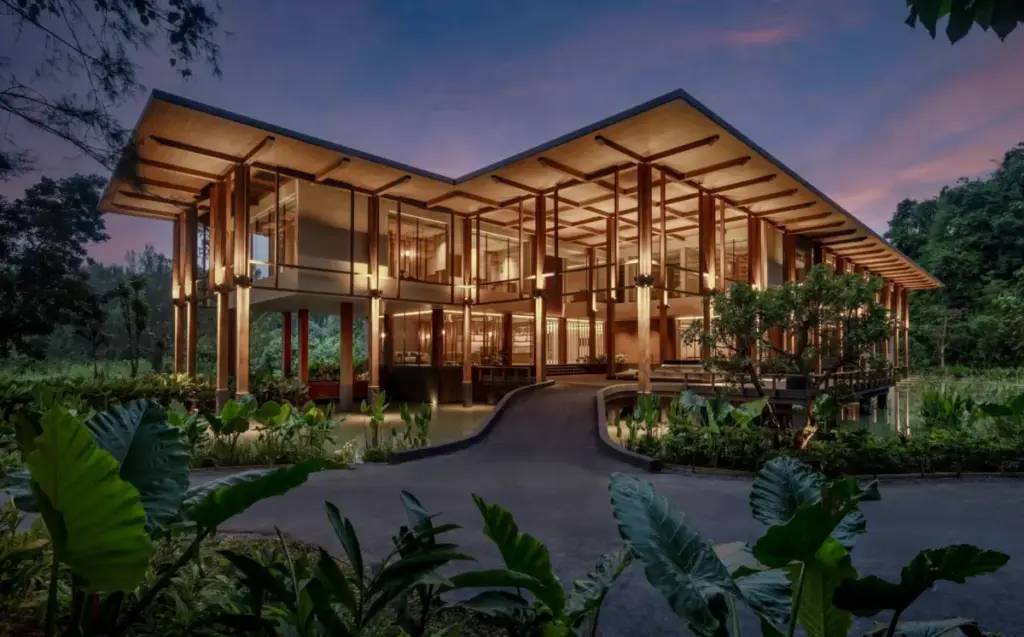
A prime example of this strategy is the company’s recent launch of Layan Life by Anantara in Phuket, Thailand. Minor Hotels invested over $11 million of its own capital to build this purpose-designed, medical wellness and longevity facility.
Instead of pitching the wellness concept to third-party owners based on theoretical projections, Minor Hotels is using the Phuket property to:
- Test Economic Viability: Prove the margins and revenue-generation capabilities of specialized medical wellness integration.
- Analyze Consumer Demand: Gather real-time data on guest stay lengths, treatment preferences, and spend-per-occupied-room patterns.
- Refine Commercialization: Optimize the distribution, marketing, and operational workflows required to run a highly complex medical-hospitality hybrid.
Once the concept has been fully optimized and its profitability proven, Minor Hotels can present a de-risked, turnkey business model to third-party owners looking to invest in the high-growth wellness sector.
"Having skin in the game doesn’t guarantee every decision will be right," Williams notes. "However, when your own capital is at risk, you feel the consequences directly. That gives you a more honest feedback loop of what worked, what didn’t, and what needs to change."
This philosophy extends behind the scenes to the property management systems that run the hotels. Before rolling out new cloud-based financial accounting systems, automated back-of-house platforms, or centralized commercial operating models to third-party properties, Minor Hotels tests and refines them within its owned hotels. This ensures that when third-party owners are asked to invest in technology upgrades, the systems are already stable, efficient, and proven to lower operating costs.
Redefining the Owner’s Due Diligence Playbook
In an era of high interest rates and compressed margins, the criteria for selecting a hotel operator must evolve. While traditional metrics like brand awareness, loyalty program membership, and global distribution reach remain important, they are no longer sufficient on their own.
Scale is valuable, but it must be balanced with operational agility. A massive loyalty program is of little use to an owner if the cost of participating in that program erodes the hotel’s net operating income, or if the operator lacks the agility to adjust property-level costs quickly when local market conditions deteriorate.
Traditional Brand Evaluation vs. The Owner-Aligned Evaluation

Traditional Operator Metrics:
• Global pipeline size (Net Unit Growth)
• Total loyalty program members
• Global brand awareness
• Standardized brand guidelines

Owner-Aligned Evaluation:
• Property-level EBITDA conversion rates
• Operator's willingness to invest own capital (Skin in the Game)
• Agility to adjust operating costs locally
• Proven ROIC on capital expenditures (CapEx)
To bridge this gap, Williams suggests that owners ask a more pointed set of questions before signing, renewing, or converting a management agreement:
- What do the operator’s global capabilities actually contribute to the individual property’s bottom line after deducting all system fees, loyalty charges, and corporate assessments?
- How quickly can the operator adapt the hotel’s labor and operating models when local economic conditions put pressure on operating margins?
- Does the operator have a proven track record of converting capital expenditure into measurable improvements in asset value and EBITDA?
- And most importantly: "If this were your money, would you still recommend that I make this investment?"
A Shared Path Forward
The debate between asset-light expansion and asset-heavy ownership does not have to be binary. As Minor Hotels’ growth trajectory demonstrates, a hybrid model that maintains real capital exposure can actually make an operator a more effective partner for asset-light owners. By keeping the real-world economics of hotel ownership visible at the corporate level, operators are better equipped to protect and grow the value of their partners’ assets.
As hotel owners navigate an increasingly complex investment landscape, the value of an operator with "skin in the game" is becoming clear. Pipeline growth may signal a brand’s ambition, but it is operational alignment and shared economic discipline that ultimately secure an asset’s long-term profitability.